New financial aid rules didn't hurt incoming law class size


The much-anticipated crisis brought on by changes in federal regulations regarding financial aid has not manifested—yet.
That’s the conclusion of law deans contacted by the ABA Journal as well as officials at the Law School Admission Council and the AccessLex Institute.
After the One Big Beautiful Bill Act killed Grad PLUS loans, which had no borrowing limits, and capped unsubsidized federal loans for “professional” advanced degrees at $50,000 annually for new graduate students enrolling after July 1, many law deans were concerned the restrictions would cause a loss of large numbers of incoming students to “summer melt”—admitted students withdrawing before the start of classes.
The worries stemmed from average total law school costs hitting $230,163, according to a July 2025 blog post by Juris Education, coupled with a December 2025 study by the Federal Reserve Bank of Philadelphia showing nearly 40% of students who would need private loans “may not be able to secure private loans without a co-signer under existing underwriting standards.”
But with many schools now in session, class sizes haven’t shrunk, and waitlists were not tapped more than usual.
Law deans contacted by the ABA Journal from Suffolk University Law School, St. Mary’s University School of Law, Quinnipiac University School of Law, Vermont Law and Graduate School, the University of California at Irvine School of Law, Widener University Delaware Law School, Santa Clara University School of Law and University of Utah S.J. Quinney School of Law each said their admissions cycle was robust and had little to no melt.
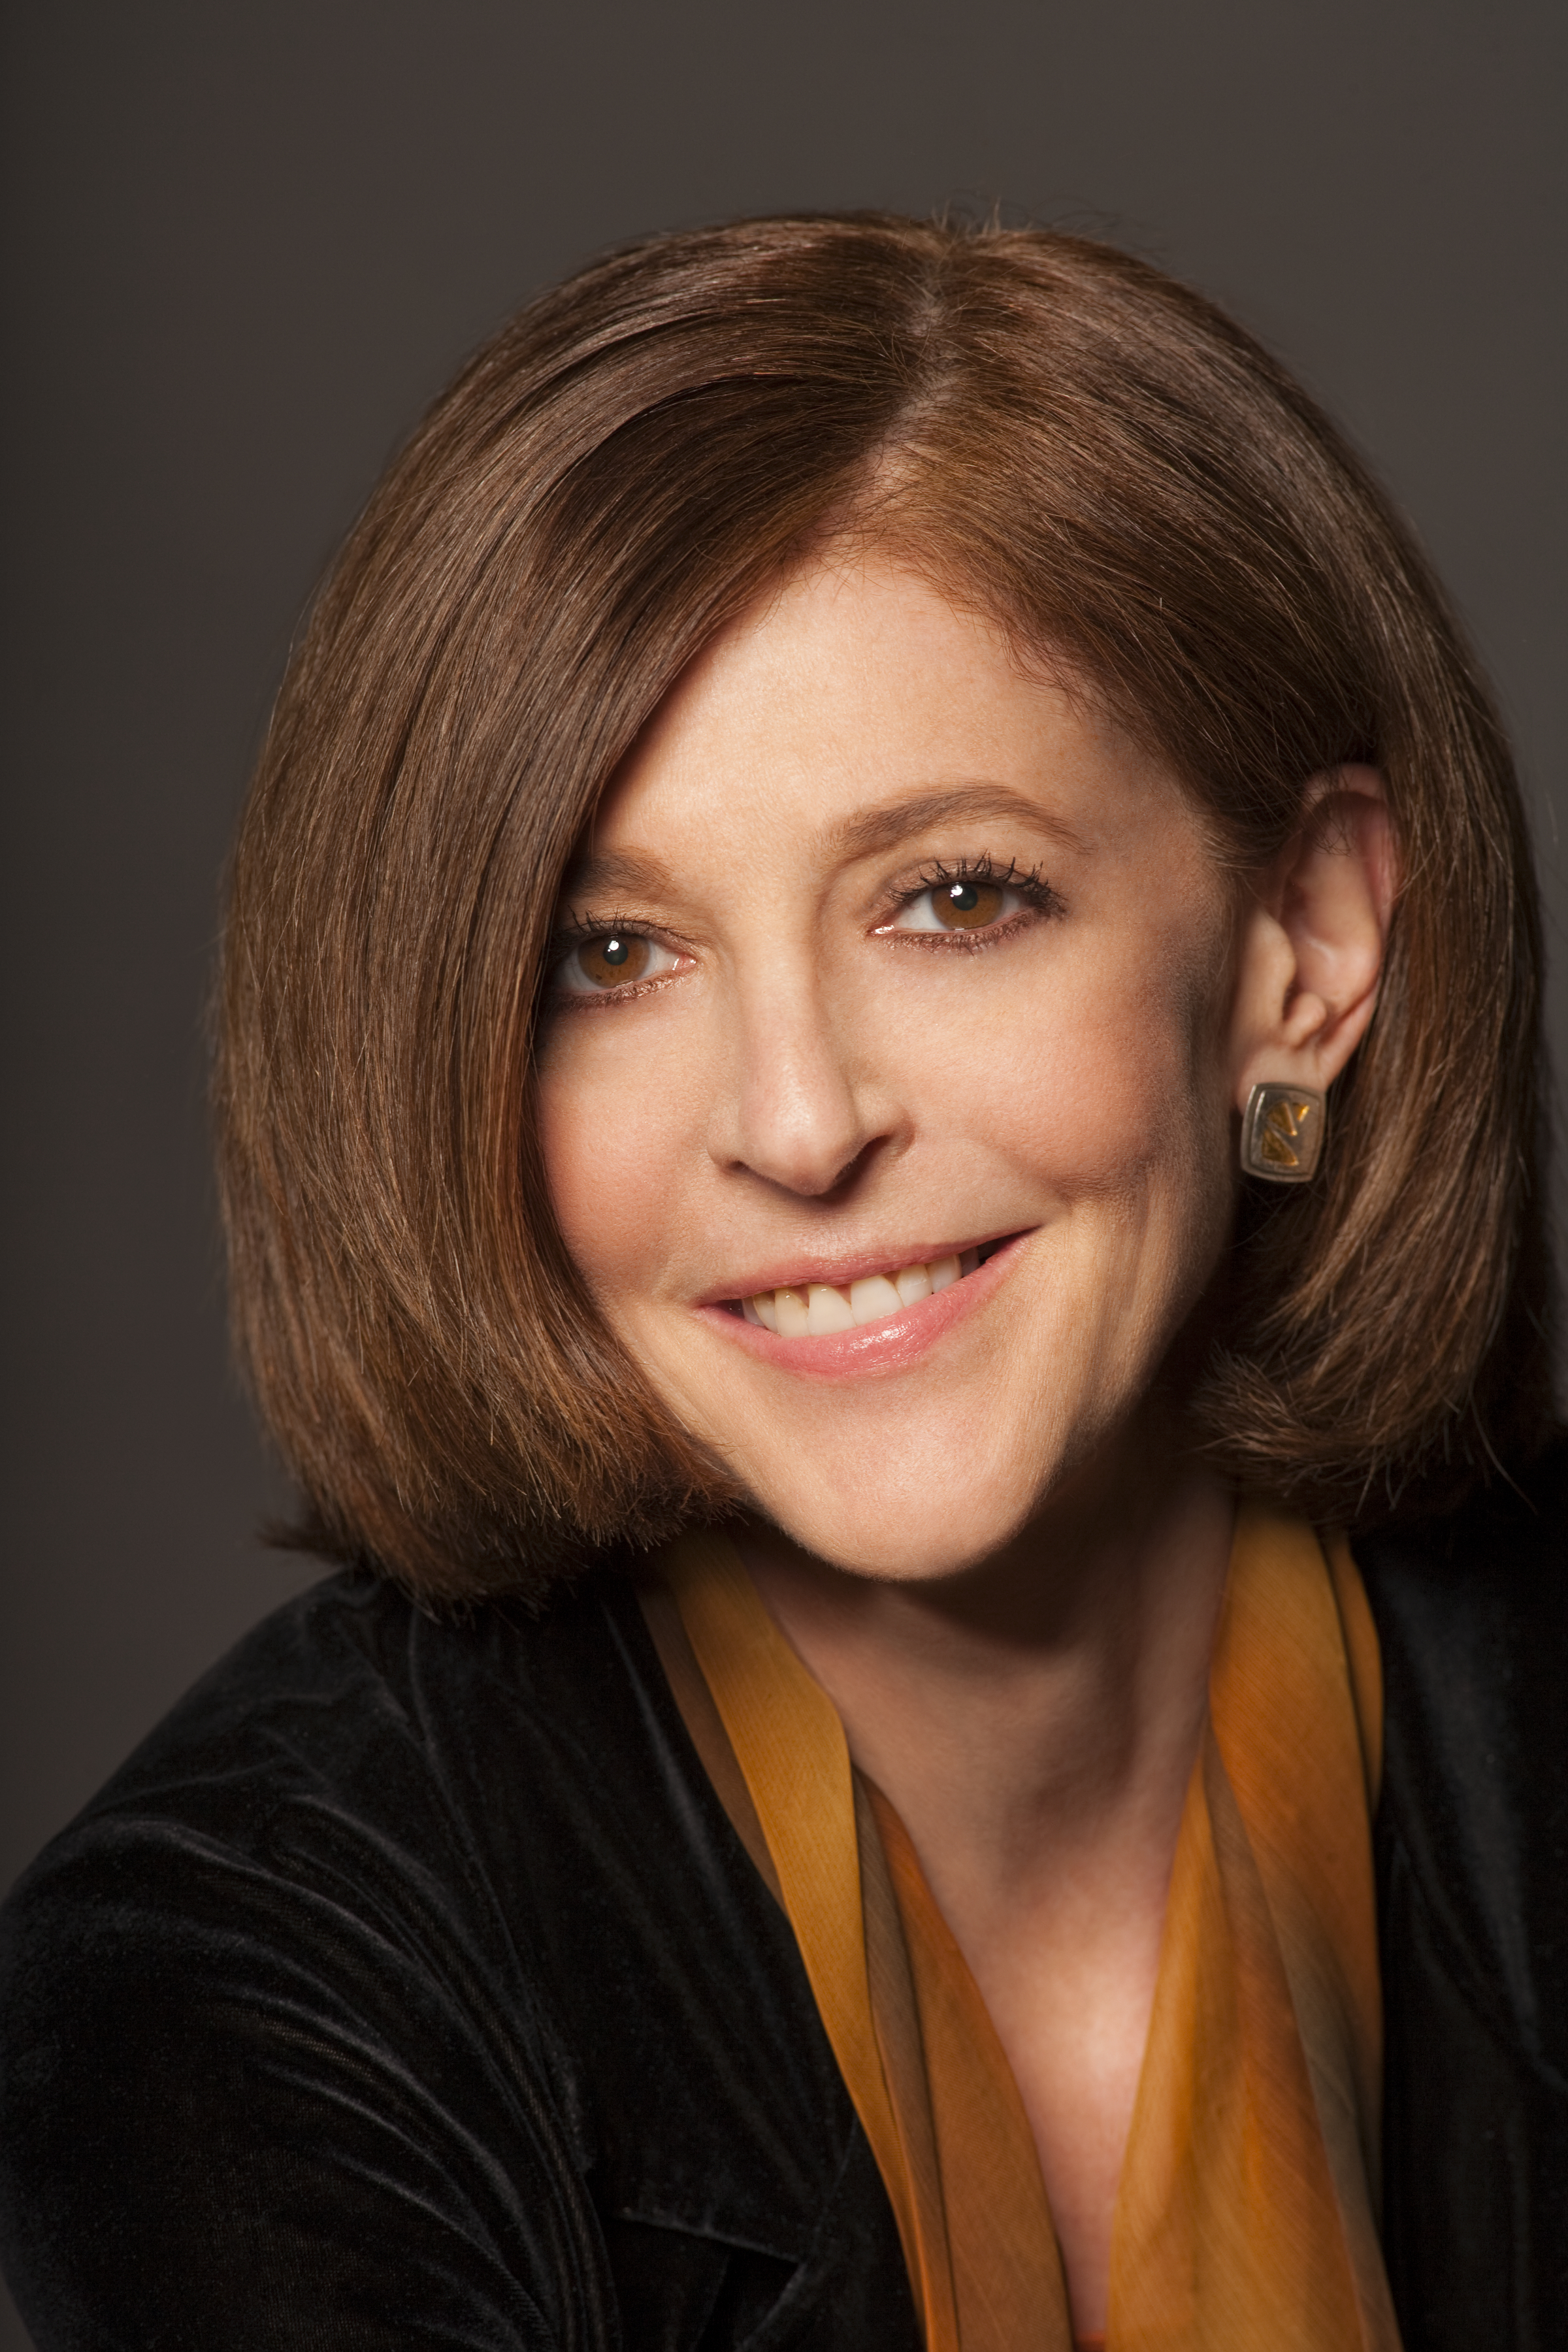
 Chris Chapman. (Photo courtesy of the AccessLex Institute)
“I’m surprised,” says Christopher P. Chapman, AccessLex Institute president and CEO.
Front-loading
While noting that data is not in to make a solid assessment on why this has happened, many of the people who spoke to the Journal say this year’s law school application boom could be masking potential issues with financial aid. Applications for fall 2026 were up 10.8% over last year and 35.5% over two years ago, according to the Law School Admission Council.
“It allows for a bigger pool of credit-eligible people in that pool,” Chapman says.
And law students could be “front-loading” their resources—pulling together all sources of cash and borrowing from their families—for their first year of law school, says Gisele Joachim, the vice president for law school engagement at the Law School Admission Council.
This year, the law impacts first-year students who took out loans after July 1, but the restrictions will be rolled out to include more classes over time.
 Gisele Joachim. (Photo courtesy of the Law School Admission Council)
“The 1Ls are gathering up every single thing that they have, and then they’ll have to borrow more as 2Ls and 3Ls,” Joachim says. “Maybe it isn’t a terrible strategy because so much rides on your 1L year in terms of your potential employment.”
But that would kick the financial aid need down the road to subsequent years, she adds, as those 1Ls will become 2Ls and 3Ls “in more of a financially difficult situation than in years past when everything was evenly distributed.”
Chapman notes there was an argument that the loan caps would reduce borrowing overall as students tighten their belts in response.
“The cap probably has led to some substitution effect,” he says. “So instead of getting your own apartment, you’re sharing an apartment, reducing your expenses.”
Opt out
Prospective students had many chances to learn about the changes: Law schools, LSAC and AccessLex conducted seminars on the topic and encouraged students to apply early for loans.
Perhaps “financially needy students opted out,” Joachim says. “They saw they’d have to borrow via private loans and didn’t bother to go through the process.”
Some law schools also might increasingly feel the pinch in years to come, Chapman adds, especially ones that created new scholarships to counteract the changes.
“Right now, they are only dealing with one cohort. If it took $100,000 to solve the issue, next year they’re going to need $200,000, and $300,000 the year after that.”
But right now, deans are reporting that all is well.
Santa Clara Law launched its Pledge Scholarship program to help its incoming students bridge tuition costs and the $50,000 federal loan limit by guaranteeing all incoming full-time 1Ls who put down a deposit by April 15 a $16,000 scholarship that won’t interfere with eligibility for other scholarships.
 Michael Kaufman. (Photo by Nic Coury)
It was “a great success,” Michael Kaufmann, dean of Santa Clara Law, told the Journal. “We experienced virtually no melt from deposit to enrollment over the summer.”
Utah Law’s yield rate (the percentage of admitted students who choose to enroll) increased to 30% from 29% last year, Dean Elizabeth Kronk Warner says, while Andrew Perlman, dean at Suffolk Law, notes, “we have not seen a noticeable difference in the percentage of admitted students who decided to enroll this fall.”
And at Quinnipiac Law, there was not a notable change, says Brian Gallini, the school’s dean. But he is hesitant to attribute any enrollment trend directly to the new aid limits.
“Any effects, if they emerge, are more likely to become apparent over the next several admission cycles rather than in the immediate aftermath of the policy change,” he adds.
Whether first-generation students and historically underrepresented students have been forced out of the law school pipeline because they didn’t have financial resources remains to be seen. That data won’t be available until early in 2027, Joachim says.
See also:
Law schools scramble to react to shifts in financial aid rules
Write a letter to the editor, share a story tip or update, or report an error.